Understanding How Lenders View Self-Employed Income
For the entrepreneurs, freelancers, and small business owners driving the vibrant economy in Massachusetts, the dream of homeownership is very real. However, navigating the mortgage process when you are self-employed can seem more complex than for those with traditional W-2 income. The good news is that it is absolutely achievable. With the right preparation and understanding, self-employed borrowers in the Boston and Plymouth areas can confidently step onto the path to homeownership.
Lenders classify you as self-employed if you own 25 percent or more of a business, work as a sole proprietor, or earn the majority of your income through 1099 contract work. This includes independent contractors, gig workers, and commission-based professionals. The primary challenge often stems from how self-employment income is reported for tax purposes. Many business owners strategically use tax deductions to reduce their taxable income. While this is financially smart for tax season, it can make your qualifying income appear lower to lenders.
Working with an experienced Boston loan officer who understands the nuances of self-employment income is the first step toward a successful application.
Essential Steps and Documentation for Mortgage Approval
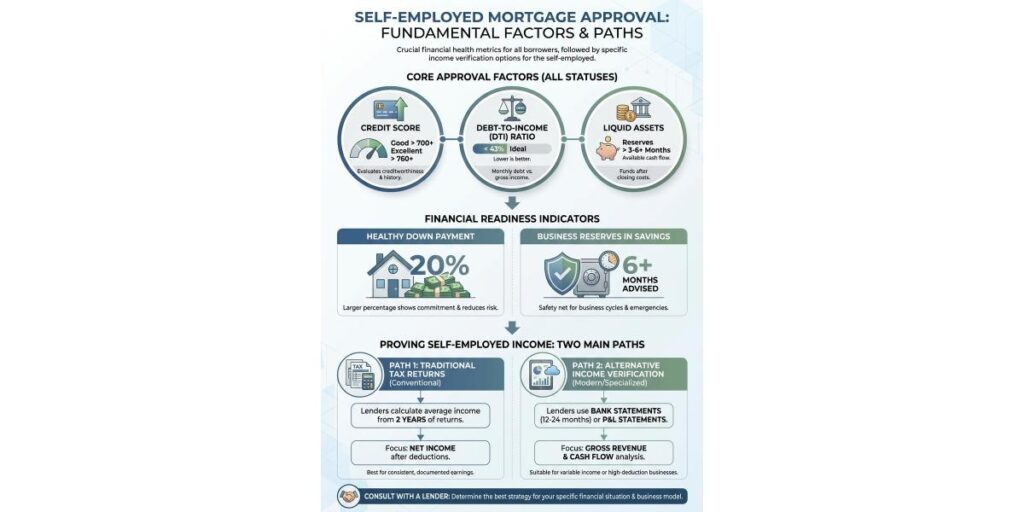
Regardless of your employment status, certain fundamental factors are crucial for mortgage approval. Lenders will evaluate your credit score, debt-to-income ratio, and liquid assets. Having a healthy down payment and at least six months of business reserves in savings is a strong indicator of financial readiness.
When it comes to proving your income, self-employed borrowers typically have two main paths:
- Traditional Tax Returns: For conventional mortgages, lenders calculate your income using your net profit from your last two years of filed federal tax returns. They will often add back non-cash expenses like depreciation to estimate your true cash flow.
- Bank Statement Loans: Recognizing the unique financial structures of self-employed individuals, many lenders offer alternative solutions. Bank statement loans allow eligible borrowers to qualify based on deposits shown in 12 to 24 months of personal or business bank statements.
To streamline your mortgage application, you should gather the following crucial documents:
- Two years of personal and business federal tax returns.
- A year-to-date Profit and Loss statement.
- 12 to 24 months of business bank statements.
- Business licenses or DBA certificates to confirm business longevity.
- Proof of funds for your down payment and closing costs.